insights : Investing in sugar
Investing in the sugar and ethanol industry
Investing in the sugar industry requires a careful understanding of agricultural economics, industrial performance, market dynamics and government policy. Despite its capital-intensive nature and long payback periods, the sector offers opportunities for long-term investors when projects are properly structured and managed.
By Patrick Chatenay - Last update : 12/10/2026
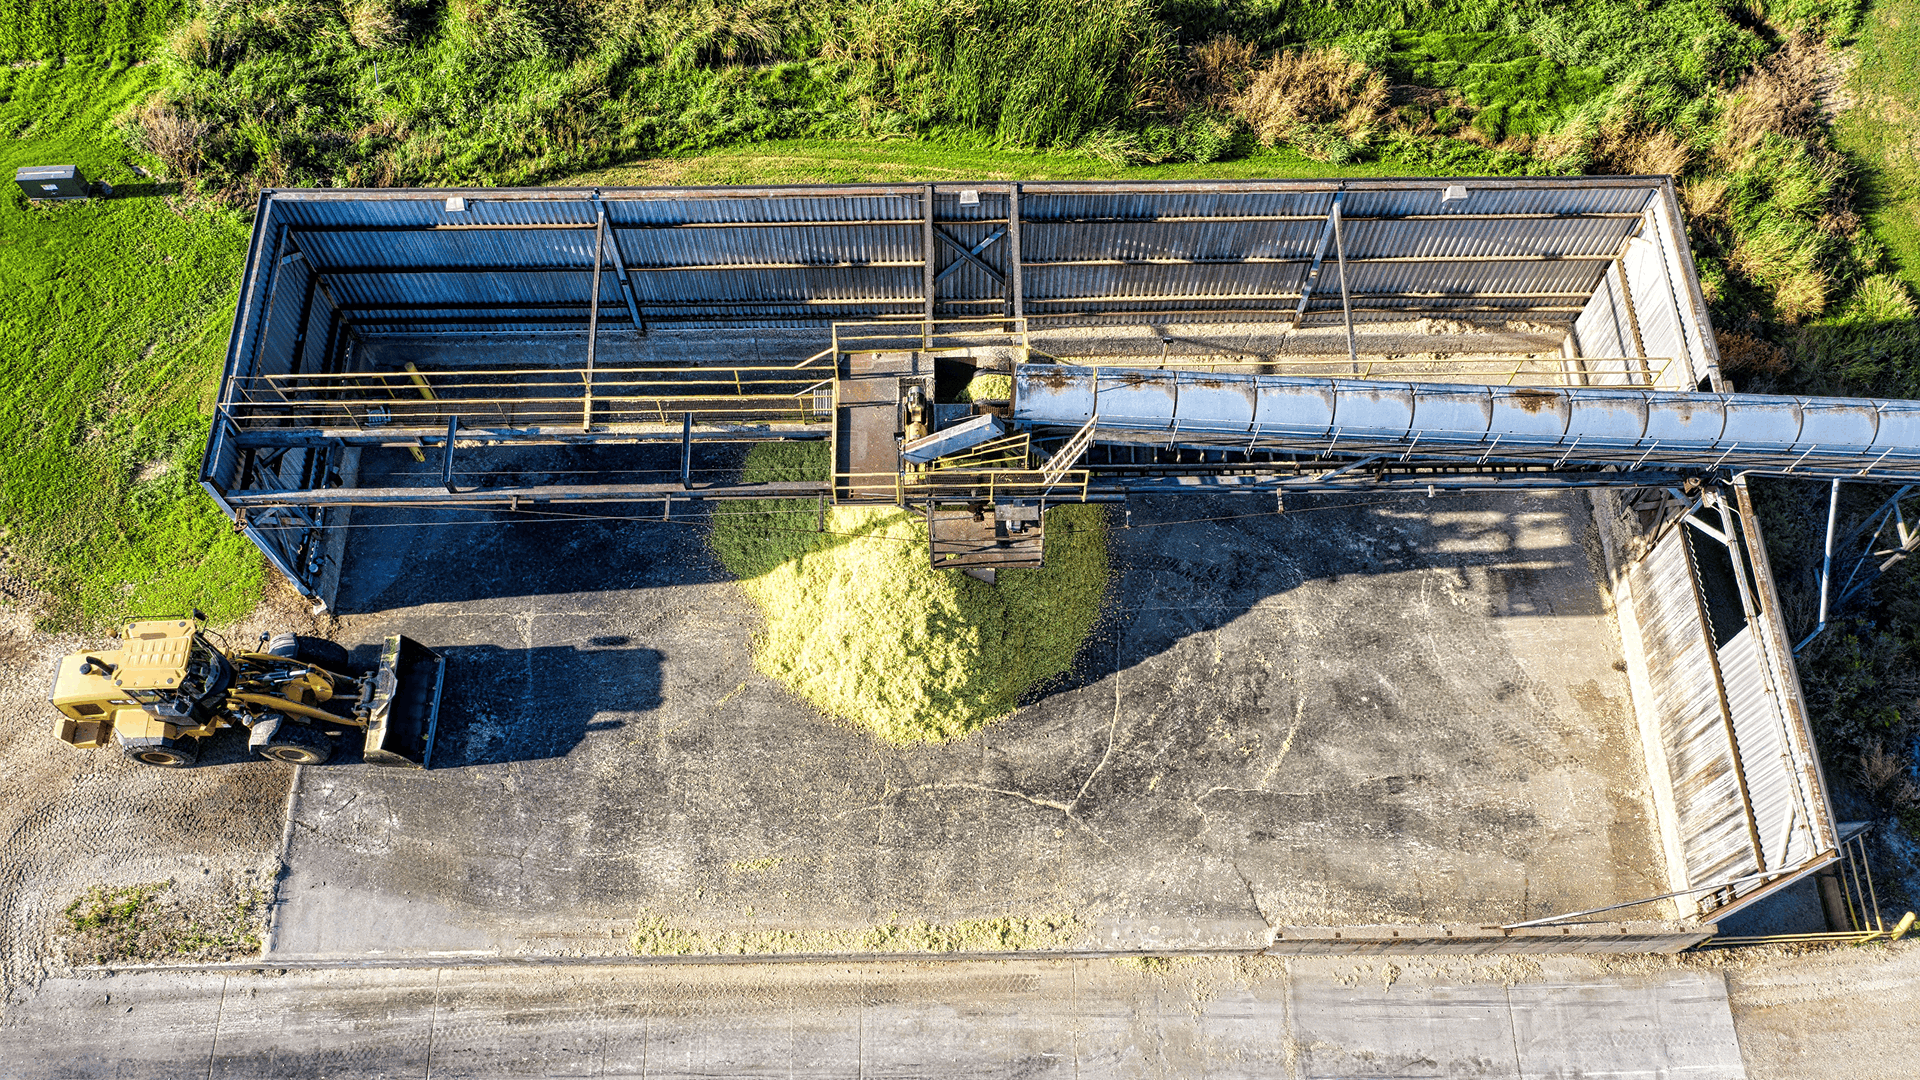
Sugarcane cultivation — a key agricultural foundation of the global sugar and ethanol industry
$170bn
Annual industry turnover
35%+
Typical mill EBITDA
$5bn
Annual long-term capital needs
1,2%
Annual world sugar demand growth, and bioelectricity and biofuel demand is enormous
$170bn
Annual industry turnover
35%+
Typicall mill EBITDA
$5bn
Annual long-term capital needs
1,2%
Annual world sugar demand growth, and bioelectricity and biofuel demand is enormous
contents
A short introduction
One good look at the sugar and ethanol industry and investors may be excused for shying away. Indeed, the industry is capital-intensive, heavily regulated and tied to farmers who are subject to large swings in output. It produces undifferentiated commodities, the prices of which fluctuate widely and for which market power is at best elusive.
World-wide per annum sugar demand growth is only 2% and ethanol demand is largely dependent upon appropriate government regulation. Worse, pay-back periods easily extend beyond 7 years; for new mills in some regions, they may reach beyond 10 years: the sugar and ethanol industry is an equity-fund nightmare.Over time, however, the financial results must be reasonable for a USD 170 billion turnover business to operate and grow. Indeed, a mill’s EBITDA typically should exceed 35%. Every year, at least USD 5 billion in long-term capital is needed to fuel expansion. In a world craving more food and more energy, sugar, ethanol and electricity supplied by this industry are essential.
Sugar and ethanol economics are complex: beyond classic industrial processing tasks, they touch upon agricultural, trade and energy issues. They thus mix public policy elements with nature, primary processing and commerce. With proper structural analysis and operational management, however, the financial rewards over time are certain.
A sample of important insights
01
With delivered agricultural raw material representing some 70% of ex-works product cost, agricultural economics are fundamental to competitiveness.
02
Because sugar beet or sugarcane deteriorate rapidly once harvested, factory capacity utilisation is constrained by the duration of the harvest.
03
Transport, both for feedstock and for finished products, is expensive; generally, it is best to produce in a deficit area so that competitors face logistical barriers.
04
For structural exporters, productivity, logistical and exchange-rate issues are paramount.
05
Stand-alone raw sugar refineries are uncompetitive where local sugar beet or sugarcane crops exist;
06
Concentration in the industry is increasing both regionally and world-wide.
To the long-term value investor, the sugar and ethanol industry offers many opportunities to protect and grow his capital.
Sugar estate and mill investment in Africa
Sugar industry success rules
Both at the farm and in the factory, the production of sugar is capital intensive: as a very general rule of thumb, an investment of two monetary units will generate annual sales of one.
A green-field operation requires a large initial capital injection (from 60 to well over 600 million US dollars, depending on the scale) and a long lead-time between the decision and the first commercial sales (4 to 7 years). Payback periods are long.
$60m-600m+
Initial investment for a greenfield operation
4-7 years
Lead-time from decision to first commercial sales
Capital intensity, financial commitment and time-to-market create risk, which is acceptable only if forecasted market prices are safe. Thus, one should not invest primarily to export sugar to the world market. Market prices fundamentally depend upon logistics and implemented trade regulations.
Market prices fundamentally depend upon logistics and implemented trade regulations.
Sugarcane accounts for between 60 and 70% of the ex-mill cost of sugar. It is therefore essential that field productivity be high (above 12 tonnes of sugar per hectare). For this to happen, cane needs:
What sugarcane needs
-
Deep soils with good drainage
-
Lots of sun, warmth (25 to 30°C during the day) and a large temperature gradient between day (warm) and night (cold)
-
Plenty of water (1500 to 2500 mm/year during its growth phase); most often, irrigation is justified
-
Rather flat land (slopes ≤ 12%)
The longer the campaign length — the time during which sugar cane is ripe — the better the industrial assets are amortized[1]. Harvesting takes place during the dry season; when the rains come, harvesting becomes difficult, if not impossible, and the sugar content of the cane is diluted.
If the campaign cannot last more than 180 days, a factory should probably not be built.
Structurally, successful sugar production depends upon farming (competitiveness) and prices obtained for the finished products (financial security).
Sugar and economic development
Economic development is best measured by the amount of fixed assets per capita — from infrastructure to light bulbs. In this sense, a sugar mill and estate are amongst the most powerful micro-economic development tools that exist.
This is notably true in rural settings in developing countries. In an area where there is precious little, a sugar mill brings roads, electricity, clean water, schools, health dispensaries and long-term jobs. In direct and indirect ways, and over a long period, a mill may offer up to 15,000 people an opportunity to join the market economy.
Further, energy is a key component of economic development and a modern sugar venture will supply electricity to the grid. In addition, depending on local regulations and fuel prices, a mill may provide ethanol for blending in petrol.
Rules of Sub-Saharan Africa
Africa presents specific challenges which favour prudence. Lessons can be learned from the way in which René LeClézio built Lonrho Sugar:
01
Safeguard market prices: government policies must support the industry
02
Minimize capital outlay: start small and install second- or third-hand equipment
03
Use a “managed contract” concept: you want a fee-based Main Contractor
04
Monitor and manage stakeholder interests; in particular, ensure local population and smallholder support
05
Aim for high leverage with long-term debt finance
06
Put your best people on the estates
07
Call on experienced operational staff to manage projects
As much as feasible, in Africa one should keep solutions inexpensive, simple and robust.
One factor warrants a special mention. In Africa, although securing long-term financing is exceptionally hard and access to land can be problematic, once a sugar project is launched, the true challenge is to ensure competent management and good execution on the ground over time.
A geolocation game
Sugar is a “geographic” business: the above elements need to be adapted to local, country and regional conditions.
With respect to sugar cane, many areas will offer appropriate farming conditions but in most of Africa land “ownership” and occupation is a delicate issue which alone may decide if a sugar operation exists.
In practise, industrial processing efficiency is not affected by the country in which it is located.
The level and behaviour of prices has to be carefully ascertained. It is best that the chosen area and neighbouring regions be net importers so that transportation costs penalise competition. It is also beneficial if consumption is of refined sugar, which costs more to move.
Distribution costs associated with the geography of consumption need to be identified. The interests of economic agents who benefit from the trade currently and may be impacted by a new supplier and, eventually, by improved border protections, should be taken into account.
Import duties and the ability to increase them if necessary[2] must be flagged — likely, this is to be at the Regional Economic Community level, taking into account other multi-lateral trade agreements. In this area, the amount and resilience of “informal” trade is an essential component of how market prices will behave.
[01]
Campaign duration determines asset utilisation, which affects economies of scale. The other scale factor is throughput (tonnes of cane processed per hour), but this element is tempered by feedstock and finished product transportation costs (distance from field to mill and from mill to consumer). Doubling campaign length reduces unit cost of sugar by about 30%; doubling daily throughput, by about 15%.
[02]
Because sugar is a commodity, price is the main competitive discriminant. Competition from imports may largely depend upon exchange rate fluctuations.
Written by
Patrick Chatenay
Founder of ProSunergy - In the sugar industry since 1985
Continue reading
Other insights
Reference analysis
Does the EU know it is killing its sugar industry
How EU sugar policy is threatening the future of Europe's domestic sugar industry
Notes
Trades, subsidies et al.
Latest : about free trade
Continue reading
Other insights
Reference analysis
Does the EU know it is killing its sugar industry ?
How EU sugar policy is threatening the future of Europe's domestic sugar industry
Notes
Trades, subsidies et al.
In the sugar industry, the past matters
Discuss a project with ProSunergy
A question about the sugar industry, an investment or a strategic issue ? Write us